Search Box

Monday, 3 June 2024

देरी से file appeal पर highcourt का आदेश *Central Goods and Services Tax Act, section107(4) read section 73 के तहत आदेश पर सुनवाई का अधिकार: Calcutta High Court का निर्णय*

*Central Goods and Services Tax Act, section107(4) read section 73 के तहत आदेश पर सुनवाई का अधिकार: Calcutta High Court का निर्णय*

 Central Goods and Services Tax Act, section 107(4) read section73- प्रस्तुत वाद में section 73 के तहत आदेश पारित करके कर के साथ interest and penalty आरोपित किया गया। याचीकर्ता ने पारित आदेश की जानकारी होते ही विलम्ब क्षमा प्रार्थना-पत्र के साथ अपील दाखिल कर दी। प्रथम अपील विलम्बित होने के आधार पर खारिज हुई जिसको challenge देते हुए 

Calcutta High Court के समक्ष writ याचिका दाखिल की गयी। याचीकर्ता का कथन है कि उसे पारित आदेश की जानकारी नहीं थी और C.A. पर भरोसा करने के कारण कर जमा करने में चूक हुई थी, अतः appeal merits and demerits पर सुनी जानी चाहिए। 

Honorable High Court ने याचीकर्ता के कथन को rational मानते हुए अभिमत दिया कि याचीकर्ता पर कर दायित्व आरोपित करने से पूर्व सुनवाई का अवसर दिया जाना आवश्यक है। Honorable Court ने प्रथम Appellate Authority को निर्देशित किया कि गुण-दोष के आधार पर अपील की सुनवाई की जाये। writ याचिका निस्तारित ।

CALCUTTA HIGH COURT in Jayshree Bhardwah vs Dy. Commissioner of Revenue (07-Aug-2023)

Saturday, 25 May 2024

Things to be remembered for Tax Regime from AY 2024-25 onwards

◾ Default Tax Regime is New Tax Regime u/s 115BAC, it means if you want to opt for Old Tax Regime then you have to select it specially in ITR Form

◾If you are filing ITR 1 or ITR 2 then you can select any regime Old or New while filing ITR and No need to file Form 10IEA for opting old tax regime for AY 24-25 and opting out of old tax regime from AY 25-26

◾If you are filing ITR 3 or ITR 4 then you can select old tax regime by Filing Form 10IEA for AY 24-25 and later on if you want to opt out of old tax regime from AY 25-26 onwards then again filing of Form 10IEA is mandatory and after that you can't opt for old tax regime again

◾For opt in or opt out of old tax regime you have to excercise option on or before due date u/s 139(1)

◾In Old Regime Tax Rebate u/s 87A is Rs.12,500/- subject to total income of Rs.5 Lakh and in New Regine Tax Rebates u/s 87A is Rs.25,000/- subject to total income of Rs.7 Lakh

◾If you have a deduction u/s 80C only or No Any Deductions then Never go for the old regime, the new regime is always beneficial & If you have claimed deductions for home loan interest, section 80C and section 80D then Never go for the new regime, the old regime is always beneficial 

◾Comparison of Deductions under Old Regime vs New Regime for FY 2023-24 (Pic 2)

◾Whatever you have opted till AY 23-24 have no impact on regime selection option from AY 24-25 (AY 24-25 is the first year for filing form 10IEA for opting old tax regime for ITR 3 or ITR 4)


Friday, 10 May 2024

व्यापारिक स्थल पर stock न होने की वजह से Registration रद्द किया जा सकता है??? ALLAHABAD HIGH COURT in M/s Shree Ram Glass vs State of U.P. (16-feb-2024)

*"क्या stock के अनुपलब्ध होने से Merchant का Registration निरस्त होना उचित है?"*


UP Goods and Services Tax Act, section 29 (2) एवं 30-प्रस्तुत वाद में Registration इस आधार पर निरस्त हुआ कि Declared place of business पर याचीकर्ता द्वारा कोई Business activity नहीं की जाती है। Revocation इस आधार पर खारिज किया गया कि स्थल Observation पर याचीकर्ता के Trading site कोई Stock नहीं पाया गया था। First Appellate Authority ने Cancellation of Registration Order की confirmed की जिसको challenge देते हुए Lucknow High Court के समक्ष writ याचिका दाखिल की गयी। याचीकर्ता का कथन है 

कि उसने अपने Filing of returns किये हुए हैं जिसे अधिकारियों ने Accepted भी किया है और firm के Bogus होने के सम्बन्ध में कोई सामग्री उपलब्ध नहीं है। Hon'ble High Court ने याचीकर्ता के कथन को उचित मानते हुए पारित Registration Cancellation आदेश समाप्त किया तथा अभिमत दिया कि ऐसा कोई कानून नहीं है जो Merchant को यह आदेश देता हो कि Trading place पर हमेशा Stock उपलब्ध रखा जाये, अतः मात्र Stock उपलब्ध न होने के आधार पर याचीकर्ता का Registration निरस्त नहीं किया जा सकता। writ स्वीकार।

ALLAHABAD HIGH COURT in   M/s Shree Ram Glass vs State of U.P.  (16-feb-2024)

देरी से file Appeal After 4 Month

*" West Bengal goods and service tax act, section 107: सीमितता अधिनियम की section 5 के प्रावधानों के संदर्भ में अपीलीय प्राधिकार द्वारा Determined किया गया समय Limit का Violation करने से संबंधित याचिका"*

West Bengal goods and services tax act, section 107 सपठित Limitation Act की section 5-प्रस्तुत वाद में अपीलीय authority ने section 107(4) के provisions के आधार पर Determined समयावधि के पश्चात् दाखिल अपील में विलम्ब क्षमा करने से इनकार कर दिया जिसको challenge देते हुए

 Calcutta High Court के समक्ष write याचिका दाखिल की गयी। याचीकर्ता का कथन है कि Limitation Act की section 5 लागू है जिसके तहत अपीलीय प्राधिकारी को Treatment सम्बन्धी बीमारी पर प्रस्तुत विलम्ब क्षमा प्रार्थना-पत्र स्वीकार करना चाहिए था। Honorable High Court ने याचीकर्ता के कथन को उचित मानते हुए विलम्ब क्षमा करके अपील इस निर्देश के साथ बहाल की कि गुण-दोष पर decided की जाये तथा अभिमत दिया कि याचीकर्ता के पास समय से अपील दाखिल न कर पाने का Sufficient कारण है। Honorable Court यह मत स्थिर किया कि Since section 107 में स्पष्ट रूप से यह नहीं कहा है कि Limitation Act की section 5 लागू नहीं होगी, अतः Appellate Authority को विलम्ब क्षमा करने का अधिकार है। writ याचिका स्वीकार।

 CALCUTTA HIGH COURT in Arvind Gupta vs Assistant Commissioner of Revenue (04-Jan-2024)
*देरी से file Appeal After 4 Month*

Monday, 18 March 2024

Rectification Applications under GST Laws: Analyzing Mistakes and Judgments

Rectification Applications under GST Laws: Analyzing Mistakes and Judgments


We all are in the process of filing Rectification Applications U/s 161 of GST Laws for "Mistake Apparent from Records."

What are the mistakes that are apparent from the records?

Let's analyze various judgments

Right of this research with: Abhishek Raja Ram

1. Delhi High Court
1.1 Food Specialities Limited (1984)
If two opinions about a question are open, then it is also not a mistake. It is only if the matter is so obvious that there can be only one answer and not much reasoning is required that one can say : It is an apparent mistake.
2. Calcutta High Court
2.1 M/s Russel Properties (P.) Ltd. (1985)
ARR: Capital gains computed on basis of one view: Failure to adopt a different view - Not a mistake apparent from the record that can be rectified.
3. Kerala High Court
3.1 M/s Ram Bahadur Thakur Ltd., Cochin
Entering into reasonableness of the expenditure claimed by the assessee in connection with the transfer - Cannot be said to be a mistake apparent from record.
3.2 Equity Intelligence India Pvt. Ltd., Cochin (2021)
Assessee claiming that Assessing Officer refused to consider Circular while issuing assessment order is not a mistake apparent on face of record to be rectified in proceedings u/S. 154. ARR
4. Andhra Pradesh High Court
4.1 P. R. N. S. and Co., Anantapur (1976)
Mistake apparent on the record must be an obvious and patent mistake, and not something that can be established by a long drawn process of reasoning on points on which there may be conceivably two opinions.
A decision on a debatable point of law is not a mistake apparent from the record.
5. Rajasthan High Court
5.1 B.L. Murarka (2001)
Only apparent mistake can be rectified - Decision on debatable point of law - Is not a mistake apparent from record.
6. Supreme Court
6.1 Saurashtra Kutch Stock Exchange Ltd (2008)
Non-consideration of the decision of the jurisdictional High Court/Supreme Court by the Tribunal - (ARR) Can be said to be mistake apparent from record.
7. Orissa High Court
7.1 Commissioner of Income-tax, Orissa v. Income-tax Appellate Tribunal, Cuttack Bench (1991)
Mistakes highlighted by assessee in order of Tribunal relating to certain erroneous conclusions -
Conclusions even if inappropriate do not constitute 'mistakes apparent from record' - Tribunal recalling its order - Not justified.

I hope you will find this useful.

Warm Regards

Abhishek Raja Ram

Saturday, 24 February 2024

How to handle GST Show Cause Notice & Draft Reply

 How to handle GST Show Cause Notice & Draft Reply


MSME 43B(h) AN INTERVIEW WITH SUDHIR HALAKHANDI BY SKH TAX TEAM

SKH TAX TEAM WITH SUDHIR HALAKHANDI

MSME 43B(H) पर SKH टैक्स टीम द्वारा सुधीर हलाखंडी के साथ एक साक्षात्कार

 MSME 43B(h) AN INTERVIEW WITH SUDHIR HALAKHANDI BY SKH TAX TEAM

-CA Sudhir Halakhandi


Respected CA Sudhir Halakhandi sir previous articles related to this issue

Click here to read this interview of Sudhir Halakhandi in Hindi.


GSTR-2A can now be downloaded in excel/CSV format for your reference and further use.

*GST PORTAL UPDATE:* 
GSTR-2A can now be downloaded in excel/CSV format for your reference and further use.

GSTN also announced that Nil return for GSTR-1, GSTR-3B and CMP-08 can now be filed through SMS.

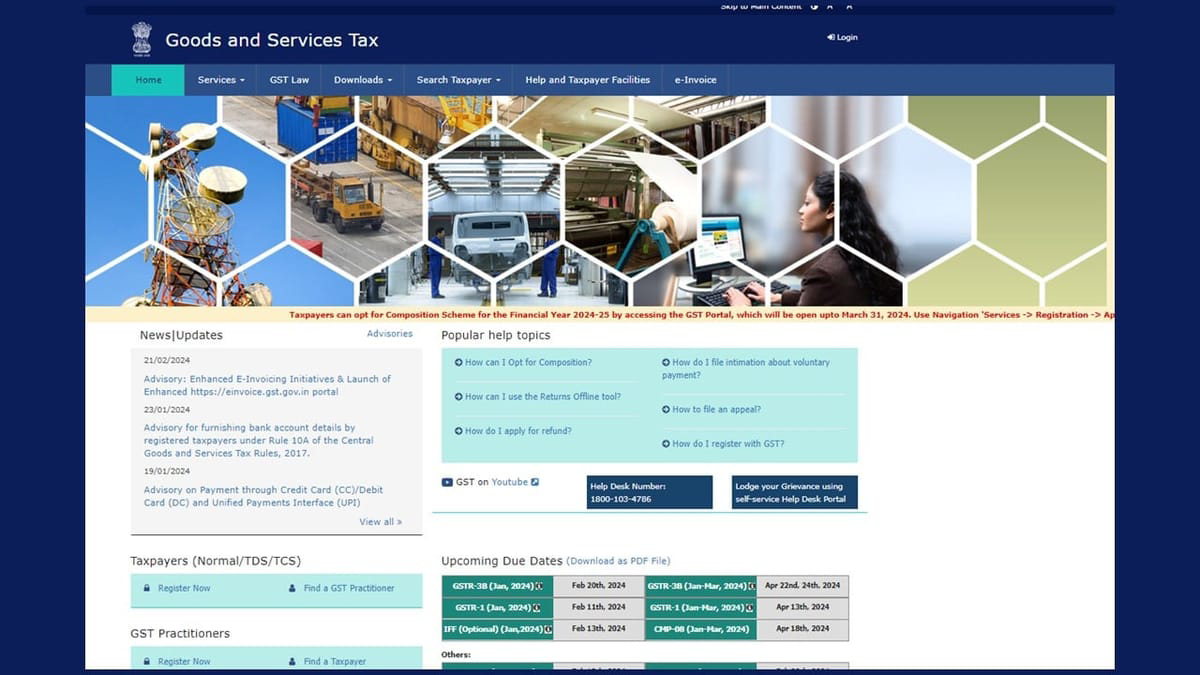
Facility for opting Composition Scheme for FY 2024-25 now live on GST Portal

*GST PORTAL UPDATE:* 
Facility for opting Composition Scheme for FY 2024-25 now live on GST Portal

The Goods and service Tax Portal has announced that Taxpayers can opt for Composition Scheme for the Financial Year 2024-25 by accessing the GST Portal, which will be open upto March 31, 2024. *Use Navigation ‘Services -> Registration -> Application to Opt for Composition Levy’, and file Form CMP-02 to opt for the same.*

Friday, 23 February 2024

DUE DATE FOR FILING REFUND CLAIM

DUE DATE FOR FILING REFUND CLAIM AS PER NOTIFICATION NO :14/2022 CT DATED 05/07/2022