


The Rajasthan High Court, Jaipur has recently issued notice in a public interest litigation challenging the constitutionality of Section 194N of the Income Tax Act, 1961.
The provision was inserted by the Finance Act, 2019 and became effective from September 1, 2019. The provision mandates the deduction of tax at source at the rate of 2% on cash withdrawals from, inter alia, a banking company exceeding Rs. 1 crore in a financial year.
The Bench of Acting Chief Justice Manindra Mohan Shrivastava and Justice Sameer Jain, observed,
"Issue notice to the respondents, returnable within four weeks. PF be filed within one week."
The plea stated,
"The validity of Section 194N providing for 2% TDS on cash withdrawals exceeding Rs. 1 crore or Rs. 20 Lakh as per their respective conditions is doubtful. Since tax to be deducted at source is on cash withdrawals which shall not be treated as income, the question of deduction of any tax at source does not arise. When the transaction is not liable to levy of income tax, the question of deduction of income tax at source with a provision for adjustment of the same against the ultimate tax liability cannot be said to be legal."
It was also added in the plea,
"Section 194N provides for deduction of income tax at source on cash withdrawal exceeding Rs.1 Crore, and the said cash withdrawal is not income liable to be taxed under the Income Tax Act, the aforesaid provision of deduction of tax at source with a provision for adjustment of the same against the ultimate tax liability of the said person, in view of the decisions of the Apex Court as well as basic objective of the Income Tax Act, is clearly ultra vires and unconstitutional."
It was also stated in the plea that in common parlance applying the Literal Rule of Interpretation on the objective of the Income Tax Act, it is very simply derived that this Act is applicable over the Income of the individual. So, charging the same on the Cash Withdrawal from Bank Account is completely against the Act and illegal in nature, added the plea.
Moreover, it was mentioned in the plea that as per the provision, tax can be deducted or collected at source only on the income of the assessee. The plea also stated that cash withdrawal from one or more accounts maintained with a bank, cooperative society engaged in the business of banking or a post office, does not involve the character of income of the recipient and hence cannot be said to be a payment. They are merely returning the money, which belongs to the recipient, on demand of the recipient, added the plea.
Hence, the petitioner alleged that cash withdrawal from banks cannot under any stretch of imagination be treated as the income generated by the recipient as one cannot make income from himself.
The plea stated,
"Section 198 of the Act states that the tax deducted at source is income received. The above section was also amended by the Notice of Amendments to Finance Bill, 2019 as introduced in the Lok Sabha on 18 July 2019 by adding a proviso to Section 198. The added provision itself intends to mean that the tax deducted on withdrawal of cash shall not be the income of an assessee and hence clearly shows that the TDS on withdrawal of cash is not on income and therefore is in violation of Section 190 of the Act."
The petitioner relied on the case of Apeejay Tea Ltd. Anr. v. Union of India, wherein Calcutta High Court granted an interim order restraining the concerned respondents authorities from deducting tax on source on the basis of the aforesaid provisions of Section 194N.Further reliance on Kanan Devan Hills Plantations Company Pvt. Ltd v. Union of India wherein a writ petition had been admitted by Kerala High Court on the same issue and accordingly an interim stay on deduction of tax on source under Section 194N of the Income Tax Act was imposed.
In addition to this, reliance was also placed on Bhawani Cotton Mills Ltd. vs State of Punjab, where while dealing with the levy of purchase tax, Supreme Court held that if a person is not liable for payment of tax at all at any time, the collection of a tax from him with a possible contingency of refund at a later stage will not make the original levy valid.
Additionally, petitioner also relied on Union of India vs. M/S Tata Chemicals Ltd., where Supreme Court observed that since there being no express statutory provision for payment of interest on the refund of excess amount/tax collected by the Revenue, the government cannot shrug off its apparent obligation to reimburse the deductors lawful monies with the accrued interest for the period of undue retention of such monies. The State having received the money without right, and having retained and used it, is bound to make the party good, just as an individual would be under similar circumstances, added the Apex court.
Further, the plea added,
"Article 265 of the Constitution of India states that "no tax shall be levied or collected except by authority of law." Further, Seventh Schedule of the Constitution of India defines and specifies the allocation of powers and functions between the Union and the States. None of the lists (Union List or Concurrent List) of the Seventh Schedule empowers the levy of tax on expenditure. Hence, the expenditure tax is unconstitutional.
The plea alleged that Section 194N will lead to deduction of huge amounts of TDS and it will result in loss in Working Capital of the Business.
Case Title: Abhay Singla v. Union of India


The Government could give input tax credit to hotel and restaurant industry which is currently not given at the current 5 percent Goods and Services (GST) tax levy, Zee Business' Tarun Sharma reports. The decision could be taken in the next GST Council meeting in April.
The GST Council is expected to take a major decision on the issue of GST on hotels and restaurants, Sharma said adding that the levy could go up from 5 percent now to 12 percent or 18 percent. It could also allow input tax credit to the industry, which till now was not available.
The demand for input tax credit was longstanding from the industry and this could now be considered during the GST council meeting, Sharma added.
A report on GST rate rationalisation is being prepared under the Chairmanship of Karnataka Chief Minister Basavaraj Bommai which is expected to be submitted in the first week of April, just ahead of the meeting of the rate rationalisation committee, Sharma said in his report.
All those hotels whose tariff is Rs 7500 or more are subjected to an 18 percent GST and can avail input tax credit.
1 फरवरी 2022
बजट 2022 अपडेट-
1. आईटीसी का दावा नहीं किया जा सकता है यदि यह धारा 38 के तहत उपलब्ध जीएसटीआर -2 बी में प्रतिबंधित है।
2. किसी वित्तीय वर्ष के इनवॉइस या डेबिट नोटों पर आईटीसी का दावा करने की समय सीमा को पहले की दो तारीखों में संशोधित किया गया है। पहला, अगले साल का 30 नवंबर या दूसरा सालाना रिटर्न दाखिल करने की तारीख।
3. धारा 38 को फॉर्म GSTR-2B के अनुरूप 'आवक आपूर्ति और इनपुट टैक्स क्रेडिट के विवरण का संचार' के रूप में पूरी तरह से नया रूप दिया गया है। यह आईटीसी दावों के तरीके, समय, शर्तों और प्रतिबंधों को निर्धारित करता है और फॉर्म जीएसटीआर -2 में निलंबित रिटर्न पर जीएसटी रिटर्न फाइलिंग में दो-तरफा संचार प्रक्रिया को हटा दिया है। इसमें यह भी कहा गया है कि करदाताओं को दावों के लिए योग्य और अपात्र आईटीसी की जानकारी प्रदान की जाएगी।
4. अनंतिम आईटीसी दावों के संदर्भों को हटाने के लिए धारा 41 को भी संशोधित किया गया है और शर्तों के साथ स्व-मूल्यांकन आईटीसी दावों को निर्धारित किया गया है।
5. अनंतिम आईटीसी दावा प्रक्रिया, मिलान और प्रत्यावर्तन पर धारा 42, 43 और 43ए को समाप्त कर दिया गया है।
29 दिसंबर 2021
GSTR-2B में प्रदर्शित होने वाले ITC के अलावा 5% अतिरिक्त ITC को हटाने के लिए CGST नियम 36 (4) में संशोधन किया गया है। 1 जनवरी 2022 से, व्यवसाय आईटीसी का लाभ तभी उठा सकते हैं जब यह आपूर्तिकर्ता द्वारा GSTR-1 / IFF में रिपोर्ट किया गया हो और यह उनके GSTR-2B में दिखाई दे।
21 दिसंबर 2021
1 जनवरी 2022 से, ITC दावों की अनुमति तभी दी जाएगी जब यह GSTR-2B में दिखाई दे। इसलिए, करदाता अब CGST नियम 36(4) के तहत 5% अनंतिम ITC का दावा नहीं कर सकते हैं और यह सुनिश्चित कर सकते हैं कि दावा किया गया प्रत्येक ITC मूल्य GSTR-2B में परिलक्षित हो।
केंद्रीय अप्रत्यक्ष कर और सीमा शुल्क बोर्ड (CBIC) ने 22 दिसंबर, 2020 की अधिसूचना संख्या 94/2020 के तहत नया नियम 86B पेश किया है। नियम 86B को 1 जनवरी 2021 से प्रभावी बनाया गया है।
नियम 86बी . से पहले आईटीसी उपयोग की अनुमति कैसे दी गई थी?
कराधान के व्यापक प्रभाव से बचकर जीएसटी में इनपुट टैक्स क्रेडिट बहुत महत्वपूर्ण भूमिका निभाता है। सीजीएसटी, एसजीएसटी और आईजीएसटी जैसे विभिन्न घटकों के लिए आईटीसी के उपयोग के क्रम में काफी बदलाव आया है। हालांकि, इलेक्ट्रॉनिक क्रेडिट लेजर में उपलब्ध आईटीसी हमेशा आउटपुट टैक्स देनदारी के निर्वहन के लिए पूरी तरह से उपयोग किया जा सकता है। नए नियम 86B ने अपनी आउटपुट टैक्स देनदारी का भुगतान करने के लिए ITC बैलेंस के उपयोग को सीमित कर दिया है।
नियम 86B के तहत क्या प्रतिबंध लगाया गया है
नियम 86बी आउटपुट टैक्स देनदारी के निर्वहन के लिए इलेक्ट्रॉनिक क्रेडिट लेजर में उपलब्ध इनपुट टैक्स क्रेडिट (आईटीसी) के उपयोग को सीमित करता है। इस नियम का अन्य सभी सीजीएसटी नियमों पर प्रभाव पड़ता है।
प्रयोज्यता: यह नियम उन पंजीकृत व्यक्तियों पर लागू होता है जिनकी आपूर्ति का कर योग्य मूल्य (छूट वाली आपूर्ति और शून्य-रेटेड आपूर्ति के अलावा) एक महीने में 50 लाख रुपये से अधिक है। प्रत्येक रिटर्न दाखिल करने से पहले हर महीने सीमा की जांच करनी होती है।
प्रतिबंध लगाया गया: लागू पंजीकृत व्यक्ति आउटपुट कर देयता के 99% से अधिक आईटीसी का उपयोग नहीं कर सकते हैं। सरल शब्दों में, इनपुट टैक्स क्रेडिट का उपयोग करके 99% से अधिक आउटपुट टैक्स देनदारी का निर्वहन नहीं किया जा सकता है।
नियम के अपवाद:
यदि नीचे उल्लिखित व्यक्तियों ने आयकर अधिनियम, 1961 के तहत आयकर के रूप में रु.1 लाख से अधिक का भुगतान किया है
पंजीकृत व्यक्ति
पंजीकृत व्यक्ति का मालिक, कर्ता या प्रबंध निदेशक
कोई भी भागीदार या पूर्णकालिक निदेशक या कोई अन्य व्यक्ति जैसा भी मामला हो।
यदि संबंधित पंजीकृत व्यक्ति को एलयूटी के तहत निर्यात के कारण या उल्टे कर ढांचे के कारण पिछले वित्तीय वर्ष में 1 लाख रुपये से अधिक की वापसी प्राप्त हुई है।
यदि चिंता के तहत पंजीकृत व्यक्ति ने चालू वित्तीय वर्ष में उक्त महीने तक कुल आउटपुट टैक्स देनदारी के 1% से अधिक की राशि के लिए इलेक्ट्रॉनिक कैश लेजर द्वारा आउटपुट टैक्स के प्रति अपनी देनदारी का निर्वहन किया है।
यदि संबंधित पंजीकृत व्यक्ति निम्नलिखित में से कोई है:
सरकारी विभाग
सार्वजनिक क्षेत्र का उपक्रम
स्थानीय प्राधिकारी
सांविधिक प्राधिकारी
व्यवसायों और कार्यशील पूंजी पर नियम 86B का प्रभाव
नियम 86बी द्वारा शुरू किए गए उपरोक्त प्रतिबंधों और अपवादों को देखने के बाद, यह स्पष्ट है कि उपरोक्त नियम केवल बड़े करदाताओं पर लागू होता है। सूक्ष्म और लघु व्यवसायों पर कोई प्रभाव नहीं पड़ेगा।
इस नियम को लागू करने के पीछे का मकसद फर्जी इनवॉयस के मुद्दे को नियंत्रित करना है ताकि फर्जी इनपुट टैक्स क्रेडिट का इस्तेमाल देनदारी के निर्वहन के लिए किया जा सके। इसके अलावा, यह धोखेबाजों को बिना किसी वित्तीय विश्वसनीयता के उच्च कारोबार दिखाने से रोकता है।
सीबीआईसी ने आगे स्पष्ट किया है कि 1% की गणना एक महीने में कर देयता और संबंधित महीने के कारोबार पर की जानी है।
चित्रण
आइए इसे एक उदाहरण की मदद से समझते हैं:
एक करदाता श्री ए ने रुपये के मूल्य के सामान की बिक्री की है। 1 करोड़ जिस पर टैक्स की दर 12% है। इस मामले में, वह आईटीसी के माध्यम से 99% तक अपनी देनदारी का निर्वहन कर सकता है और रुपये का भुगतान करना होगा। 12,000 नकद में, इस नियम के अनुसार।
हालांकि इस नियम ने वास्तविक करदाताओं को भी उनके लिए असुविधाजनक बना दिया है, लेकिन सरकार का मकसद नकली चालान से बचना और अंततः कर चोरी पर अंकुश लगाना है।
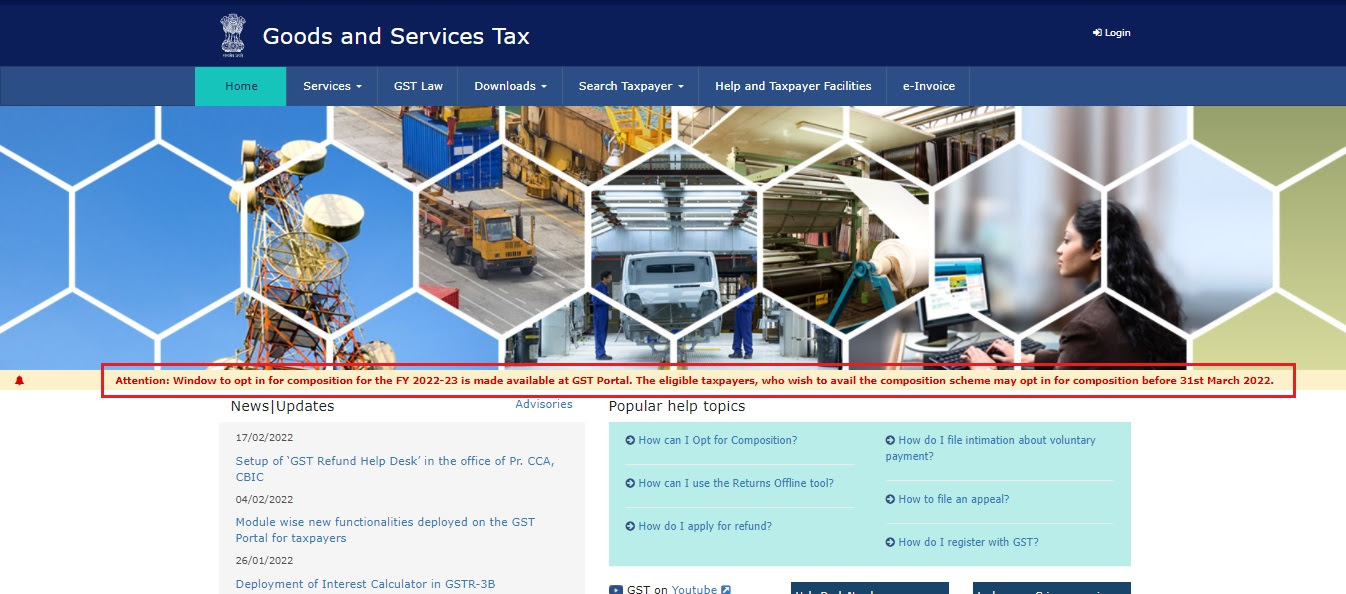
The Goods and Services Tax Network (“GSTN”) has enabled window to opt in for composition scheme for the FY 2022-23 on GST Portal for the taxpayers.
The eligible taxpayers, who wish to avail the composition scheme may opt in for composition before March 31, 2022.
Source from: https://www.gst.gov.in/


